Marketing ROI (return on investment) sounds like a simple ratio, but most 'ROI' figures reported inside ad platforms or marketing dashboards are incomplete. They usually compare attributed revenue to ad spend alone, ignoring other real costs and skipping the question of whether that revenue would have happened anyway. This article builds a complete reconciliation so you can report a number you can actually defend.
Step 1: Define the decision and reporting window
Before calculating anything, decide what period you are evaluating and why. A single week of ad data is rarely enough to judge ROI, because costs (like a one-off production project) and revenue (which may lag behind the click that generated it) often fall in different periods. Choose a window long enough to capture at least one typical buying cycle, commonly a month or a quarter for most small and mid-sized businesses, and be consistent about it when comparing periods.
Step 2: Reconcile all real costs, not just ad spend
Ad spend is usually the most visible cost, but it is rarely the only one. A complete reconciliation includes:
- Ad spend: the amount paid directly to the advertising platform.
- Agency or freelancer fees: any management or production fee paid to run the campaign.
- Production costs: creative, copywriting, photography, or video costs attributable to the campaign.
- Platform or tooling fees: software, landing page builders, or tracking tools used specifically for the campaign.
- Product and fulfilment costs: the cost of goods sold or service delivery cost for whatever was actually purchased.
- Refunds and returns: revenue that was later reversed and should not be counted as a final outcome.
Step 3: Convert revenue into contribution profit
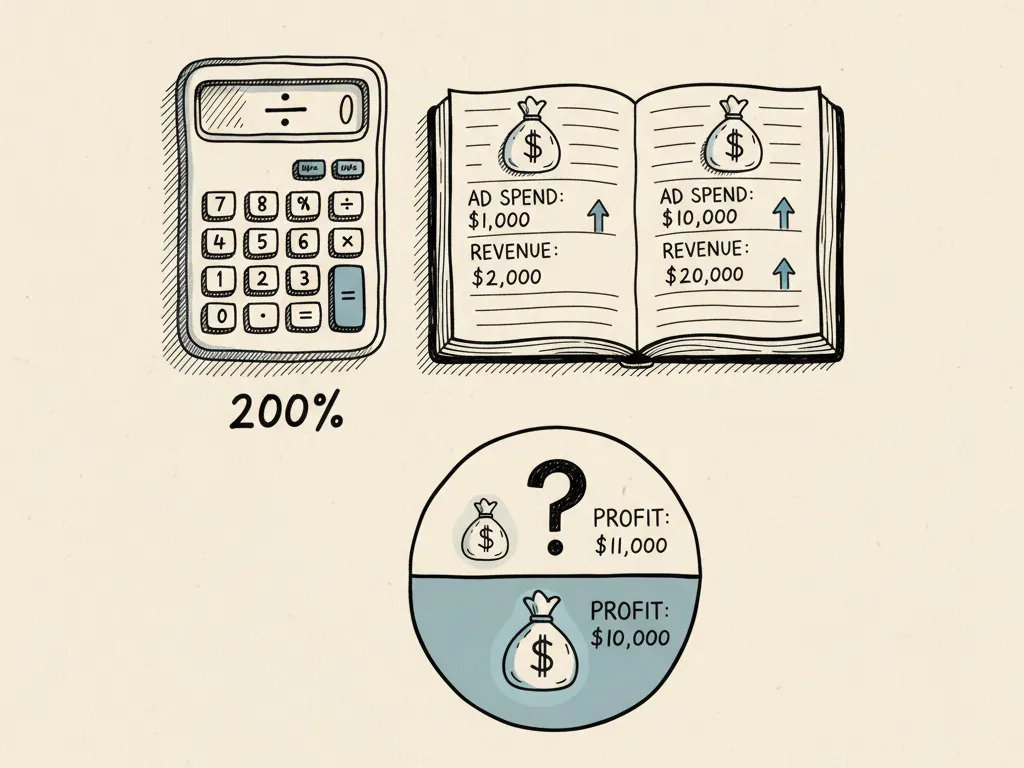
Revenue is the top-line amount a customer paid. Contribution profit is what remains after subtracting the direct costs of delivering that sale (cost of goods, fulfilment, payment processing), but before fixed overhead like rent or salaries. Comparing marketing cost to raw revenue overstates performance; comparing it to contribution profit gives a realistic picture of whether the campaign made the business more money than it spent.
- 1Record attributed revenue for the window from your reporting tool or platform
- 2Subtract refunds and returns within the same window
- 3Apply your contribution margin to get contribution profit before marketing costs
- 4Subtract total marketing cost (ad spend + agency + production + tooling)
- 5Report the resulting contribution profit after marketing cost, not just a ROAS multiple
Step 4: Account for lag
Spend in one period often produces outcomes in a later period, especially for longer buying cycles or content that keeps attracting traffic after publication. If your reporting window is shorter than your buying cycle, you will systematically understate ROI because much of the resulting revenue has not landed yet. Where possible, track cohorts by the date the marketing touchpoint occurred, not the date revenue was recorded, so lag doesn't distort the picture.
Step 5: Separate attribution from incremental, causal evidence
Attributed revenue is what a platform or analytics tool credits to a specific marketing touchpoint, usually the last click or a modeled split across touchpoints. It is useful for day-to-day optimization but it is not proof that the revenue would not have happened without the marketing. Some portion of 'attributed' sales may represent customers who would have purchased anyway, found you through another channel, or were already loyal. Incremental evidence comes from comparing outcomes against a counterfactual, for example a holdout group that didn't see the campaign, or a geo-based test where some regions ran ads and others didn't. Incremental evidence is harder to produce but far more reliable for big, ongoing budget decisions.
| Attributed (platform/model credit) | Incremental (causal, experiment-based) |
|---|---|
| Easy to generate, available immediately | Requires planning a holdout or geo test in advance |
| Can overstate impact from customers who'd have bought anyway | Isolates the effect that marketing actually caused |
| Good for day-to-day optimization decisions | Good for large, ongoing budget commitments |
| Vulnerable to platform self-reporting bias | More resistant to bias, but needs more volume and time |
A worked ROI reconciliation and reporting template
Use this template each reporting period so the same cost categories and definitions are applied consistently.
- Reporting window defined (start and end date) and matched to a realistic buying cycle
- Attributed revenue pulled from a single source of truth (not mixing platform dashboards)
- Refunds and returns subtracted within the same window
- Contribution margin applied and documented (what costs it already excludes)
- All marketing costs listed: ad spend, agency/freelancer, production, tooling
- Contribution profit after marketing cost calculated and reported alongside ROAS, not instead of it
- Noted whether this figure is attributed or incremental, and what evidence supports causality
- Next review date set, matched to the next full buying cycle
Common mistakes
- Reporting ROAS (revenue divided by ad spend) and calling it profit, when it has not accounted for product cost or other marketing costs.
- Leaving out agency fees, production costs, or tooling costs because they feel like 'overhead' rather than marketing cost.
- Using a reporting window shorter than the business's actual buying cycle, which understates real results.
- Treating all attributed revenue as proof the marketing caused the sale, with no holdout or control to check.
- Mixing revenue and contribution profit in the same report without labeling which is which.
When this reconciliation is not necessary
For very small, low-stakes tests, for example a one-week $200 ad test to validate a new creative angle, a full profit reconciliation can be overkill; a simple directional comparison of cost per qualified lead against history may be enough to decide whether to continue testing. Full reconciliation becomes essential when a decision involves a meaningful share of budget, a recurring commitment, or when you are reporting results to stakeholders who will make resourcing decisions based on the number.
Where to go next
Read the article on what counts as a good ROAS for how to set margin-aware break-even targets before you even reach ROI reporting, and the attribution model article for how to choose a measurement approach that matches your business's complexity.