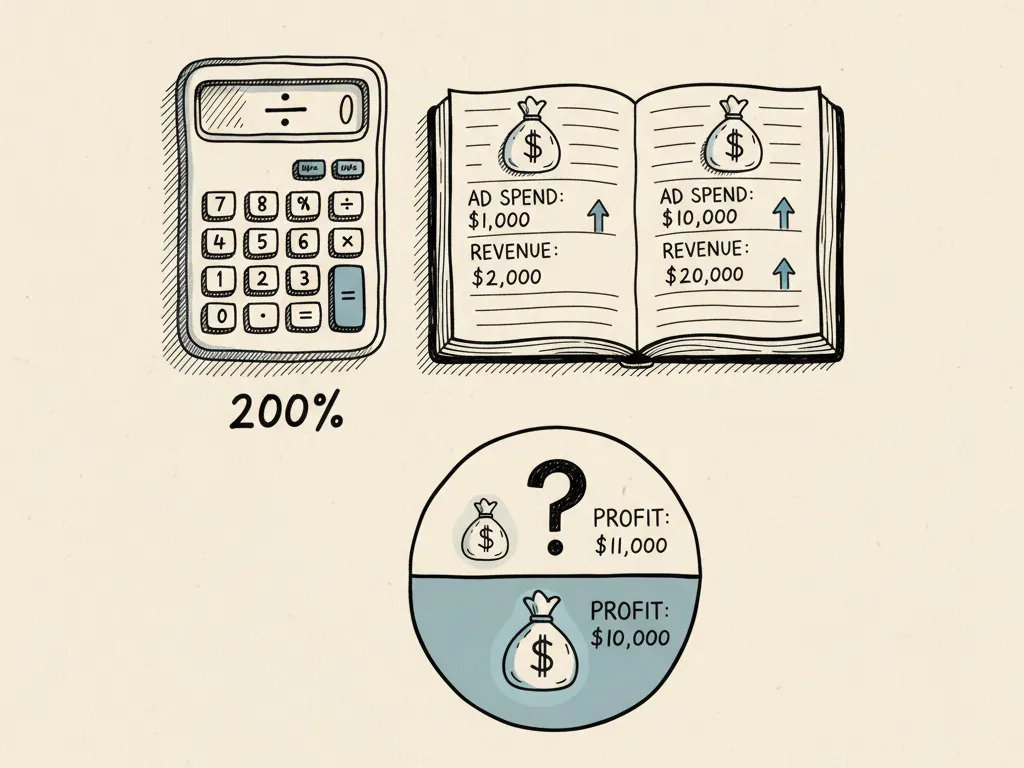
'What is a good ROAS?' is one of the most searched questions in paid advertising, and most answers give a single number, often somewhere around 3x or 4x, as if it applied to every business. It does not. ROAS (return on ad spend) is attributed revenue divided by ad spend; it says nothing on its own about profit, because it ignores your margin, your other costs, and whether that revenue is attributed correctly. This article builds a margin-aware break-even model so you can judge your own ROAS instead of borrowing someone else's benchmark.
Start with the break-even ROAS formula
Your contribution margin is the percentage of revenue left after the direct costs of delivering that revenue (product cost, fulfilment, payment processing) but before marketing costs. Your approximate break-even ROAS, the point at which ad spend alone is covered by the contribution it generates, is 1 divided by your contribution margin percentage expressed as a decimal.
Add non-ad marketing costs, refunds, and fees
Ad spend is rarely the only marketing cost. Agency fees, software, creative production, email platform costs, and affiliate commissions all reduce what a given ROAS actually delivers in profit. Refunds and chargebacks reduce the revenue a campaign is credited with generating in the first place, and payment processing fees take a further cut before any contribution reaches the business.
Distinguish new and returning customers
A blended ROAS figure can hide an important difference: revenue from returning customers who already knew your brand is often not fully attributable to the specific ad that happened to show them a retargeting message, while revenue from genuinely new customers is a stronger signal of acquisition performance. If your reporting does not separate new-customer ROAS from returning-customer ROAS, a healthy blended number can mask a weak new-customer acquisition engine propped up by repeat buyers who may have returned anyway.
| Customer type | Attribution confidence | What it tells you |
|---|---|---|
| New customer | Higher, since the ad likely introduced them to the brand | Closer proxy for acquisition performance |
| Returning customer | Lower, since they may have returned without seeing the ad | Can inflate blended ROAS without reflecting new growth |
Three hypothetical scenarios: same ROAS, different outcomes
The table below shows three clearly hypothetical businesses, each reporting the same 4.0x attributed ROAS on $5,000 of ad spend and $20,000 of attributed revenue, but with different contribution margins and other costs, producing very different actual contribution after marketing costs.
| Scenario | Margin | Other marketing costs | Contribution after marketing costs |
|---|---|---|---|
| A: higher-margin services business | 70% | $1,500 | $20,000 x 70% - ($5,000 + $1,500) = $7,500 |
| B: mid-margin ecommerce brand | 45% | $2,500 | $20,000 x 45% - ($5,000 + $2,500) = $1,500 |
| C: low-margin retail reseller | 25% | $2,000 | $20,000 x 25% - ($5,000 + $2,000) = -$2,000 |
All three scenarios share an identical 4.0x ROAS, yet scenario A is comfortably profitable after marketing costs, scenario B is marginally profitable, and scenario C is actually losing money once the full marketing cost is included. This is why a single 'good ROAS' target applied across businesses with different margins is misleading at best.
Attributed ROAS versus incremental outcomes
Everything above uses attributed revenue, meaning revenue a platform or analytics tool credits to a given ad based on a tracking model. Attributed revenue is not the same as incremental revenue, the revenue that would not have happened without the ad. Some attributed purchases would likely have occurred anyway (a customer who already intended to buy and simply clicked an ad on the way), which means true incremental ROAS is often lower than attributed ROAS. Establishing actual incremental impact generally requires a controlled approach such as a holdout test, which is a separate undertaking from day-to-day reporting.
Your break-even model checklist
- Calculate your contribution margin after product, fulfilment, and processing costs, before marketing
- Calculate ad-only break-even ROAS as 1 / contribution margin
- Add your actual other marketing costs (agency, software, production) to find total marketing cost
- Recalculate break-even ROAS including these other costs
- Separate new-customer and returning-customer ROAS wherever your reporting allows it
- Treat attributed ROAS as a directional signal, not proof of incremental profit, unless supported by causal testing
Common mistakes
- Adopting a single 'good ROAS' number from a blog post or competitor without calculating your own margin-based break-even.
- Ignoring refunds, processing fees, and non-ad marketing costs when judging whether a ROAS figure is actually profitable.
- Reporting only blended ROAS and missing that returning customers may be inflating the number without reflecting new growth.
- Treating attributed revenue as proof of incremental revenue without acknowledging the difference.
- Comparing ROAS across campaigns or businesses with very different margins as if the number alone were comparable.
When this is not the right tactic
A margin-based ROAS model is less useful if you do not yet know your true contribution margin, in which case the first priority is proper cost accounting, not more precise ad measurement. It is also less relevant for campaigns explicitly designed for brand awareness or long-term customer acquisition rather than immediate direct response, where short-window ROAS was never the right metric and other measures (reach among a defined audience, brand lift, or longer-window customer value) matter more.