Most businesses can state a single blended customer acquisition cost (CAC, total acquisition spend divided by new customers) and a single lifetime value (LTV) estimate. Fewer can explain which customers those numbers describe, over what period, or what happens if retention comes in lower than hoped. A cohort model fixes this by grouping customers by acquisition period and channel, then tracking their costs and contribution over time with transparent, checkable formulas.
What a cohort is and why it matters
A cohort is a group of customers who share an acquisition period, commonly the month they first purchased, and often a channel or campaign. Tracking cohorts separately, rather than looking only at blended monthly totals, reveals whether unit economics are improving or deteriorating as the business scales, and whether a channel that looks cheap on CAC alone is actually producing customers who stick around.
Revenue LTV versus contribution-margin LTV
Revenue LTV sums the revenue a cohort generates over a defined window. Contribution-margin LTV applies the business's contribution margin (revenue minus the variable costs of delivering the product, such as cost of goods, payment processing, and fulfilment) to that revenue, so it reflects what is actually available to cover acquisition cost and fixed costs. Revenue LTV is useful for forecasting top-line growth; contribution-margin LTV is the correct basis for CAC payback and for deciding how much you can afford to spend to acquire a customer.
Building the model: a worked hypothetical
Allocating CAC consistently
CAC allocation decisions change the answer substantially, so document them explicitly. Decide whether CAC includes only media spend, or also creative production, tools, and a share of marketing salaries. Decide the attribution window (the period after an ad interaction during which a resulting purchase is still credited to that spend) and keep it consistent across cohorts so comparisons are fair. When channels are mixed (for example, a customer who saw an ad and later converted through organic search), document the attribution method used rather than silently picking whichever channel looks best.
Accounting for retention and refunds
Retention curves are rarely flat; they typically decline fastest in the earliest periods and then flatten. Model retention explicitly by period rather than assuming a constant rate forever, and separate refunds and chargebacks from genuine churn, since a refunded sale should reduce both revenue and the acquisition cost it was meant to repay, not just disappear from a later period. For physical products, include returns and the cost of processing them; for subscriptions, separate voluntary cancellation from failed-payment churn, since the two usually need different fixes.
Why early behavior should not be projected indefinitely
A common forecasting error is observing strong retention in the first one or two periods of a brand-new cohort and extrapolating that rate for years. Early adopters of a product or offer are frequently more engaged than later, broader customers, so projecting month-one or month-two retention out to month twenty-four typically overstates long-run LTV. Use the longest actual observation window available, and apply a conservative decay assumption beyond it, stated explicitly as an assumption rather than presented as measured fact.
Comparing cohort payback across periods
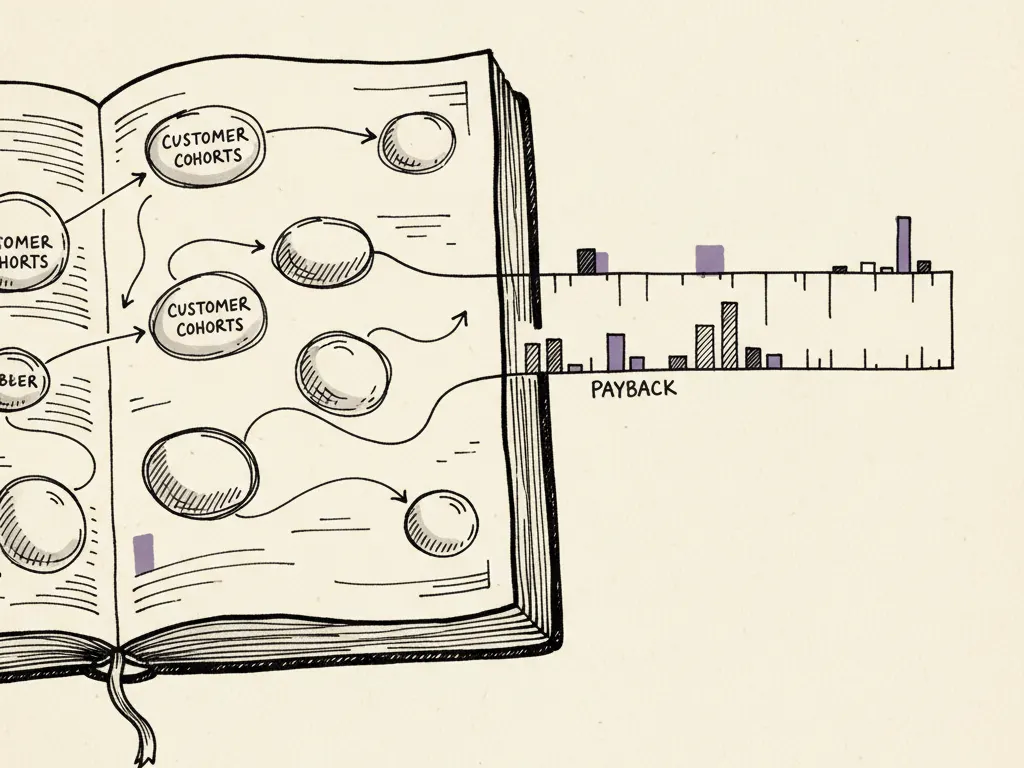
Illustrative values in months to reach cumulative contribution margin equal to CAC; not client results.
Watching payback period trend across cohorts, rather than any single cohort in isolation, shows whether acquisition efficiency is improving, worsening, or simply noisy month to month. A rising trend across several consecutive cohorts, as in the illustrative April cohort above, is worth investigating even if every individual cohort still eventually pays back.
Using low, base, and high scenarios
Because retention, refunds, and future pricing are uncertain, present three scenarios rather than one number: a low scenario using conservative retention and margin assumptions, a base scenario using current observed trends, and a high scenario using optimistic but plausible assumptions. Decision-makers should see the range, and the assumptions behind each scenario, not just the base case.
| Scenario | Month-2 retention assumption | 24-month contribution LTV (illustrative) | Payback period (illustrative) |
|---|---|---|---|
| Low | 65% | $220 | 7 months |
| Base | 80% | $340 | 4 months |
| High | 88% | $410 | 3 months |
A cohort model framework
- 1Define the cohort grouping (acquisition month and, if relevant, channel)
- 2Allocate CAC consistently, documenting what costs and attribution window are included
- 3Track revenue, contribution margin, refunds, and retention by period for each cohort
- 4Calculate cumulative contribution-margin LTV and identify the payback period
- 5Build low/base/high scenarios and compare payback trends across recent cohorts
Common mistakes
- Using revenue LTV to justify acquisition spend when contribution-margin LTV is the number that matters for profitability.
- Projecting early-cohort retention rates indefinitely without a decay assumption.
- Allocating CAC inconsistently between cohorts, making trend comparisons meaningless.
- Ignoring refunds and chargebacks, which overstates both revenue and true contribution.
- Presenting a single-point LTV forecast instead of a range that reflects real uncertainty.
When this is not the right tactic
Full cohort modeling is most valuable once a business has at least several months of repeat-purchase or renewal data across multiple acquisition periods; a brand-new product with no retention history yet cannot support anything beyond a simple, clearly labeled hypothetical model. Very low-volume businesses (a handful of customers per month) will also find cohort-level detail statistically unreliable and may be better served by simpler, blended CAC and gross-margin tracking until volume grows.